Market overview and structural significance of the Semiconductor Graphite Market
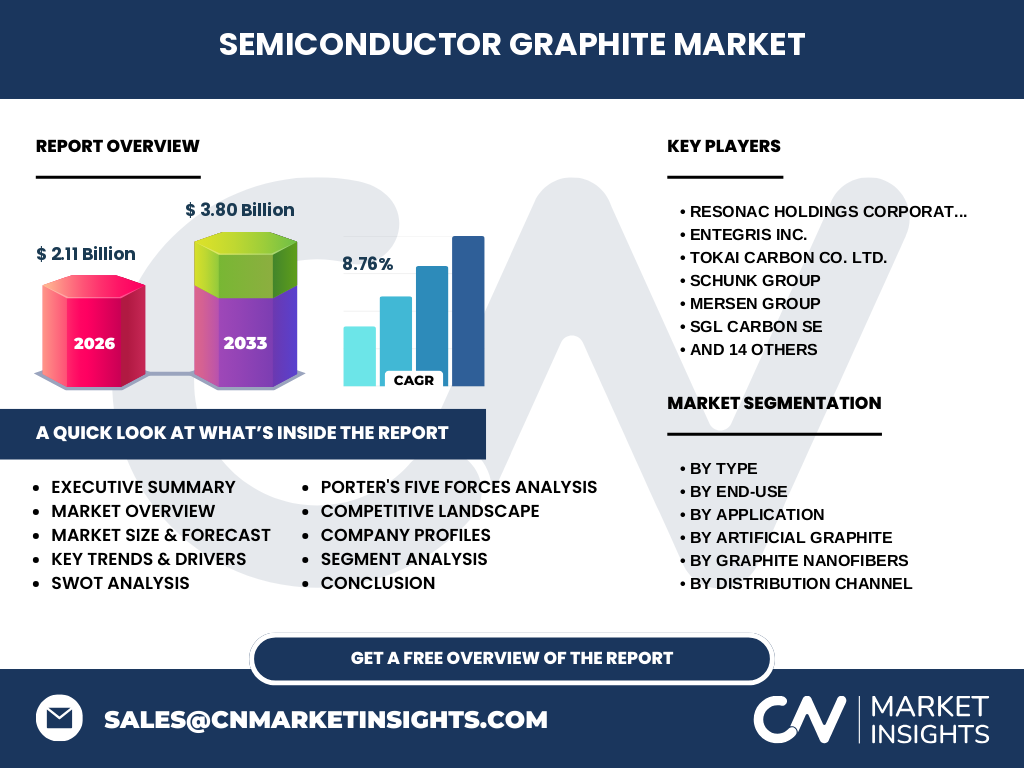
Our analysis indicates that the Semiconductor Graphite Market reached a valuation of 2.11 Billion in 2026. This specialized sector provides ultra-high-purity isotropic graphite essential for crystal pulling crucibles, epitaxial reactors, and susceptors. Industry participants like Resonac Holdings Corporation and Tokai Carbon Co. Ltd. anchor this ecosystem, supplying critical components that withstand extreme thermal and chemical environments during wafer fabrication.
Structural Growth Drivers and Market Restraints
The market thrives on surging demand for advanced node logic and memory chips, though constrained by strict environmental regulations on graphitization emissions governed by agencies like the EPA and EU directives. Supply chain bottlenecks for needle coke raw materials pose ongoing operational hurdles. Conversely, extreme ultraviolet lithography advancements create lucrative opportunities for high-purity synthetic graphite blocks.
Emerging Trends in the Semiconductor Graphite Industry
The shift toward wide bandgap semiconductors made from silicon carbide and gallium nitride demands ultra-pure synthetic graphite powder and advanced thermal management solutions. Manufacturers are increasingly adopting Isostatic graphite grades to reduce defect densities in 300mm wafer processing equipment, driving a technological evolution across global fabrication facilities.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
Pandemic-era supply chain disruptions temporarily stalled fab expansions, yet accelerated long-term automation investments. Our research shows that post-COVID recovery spurred aggressive localization of raw material processing, compelling companies like Mersen Group and SGL Carbon SE to regionalize inventory hubs near major semiconductor manufacturing clusters in East Asia and North America.
Competitive Benchmarking and Market Concentration
The competitive landscape features high market concentration among established chemical innovators such as Entegris Inc., Toyo Tanso Co.Ltd., and Graphite India Limited. These industry leaders maintain a competitive moat through proprietary purification techniques capable of achieving ash content below 5 parts per million, safeguarding their dominance in tier-one semiconductor supply chains.
Executive Summary of the Semiconductor Graphite Industry
Valued at 2.11 Billion in 2026, the sector is projected to expand to 3.80 Billion by 2033 at a robust CAGR of 8.76%. Driven by automotive electrification and advanced node scaling, market leaders are aggressively investing in high-purity synthetic graphite blocks and customized conductive coatings to capture high-margin foundry contracts.
Market Forecast from 2027 to 2033
Driven by sustained demand for high-performance computing hardware, the market is forecasted to scale from 2.11 Billion in 2026 to 3.80 Billion by 2033, achieving an impressive 8.76% CAGR. This trajectory is underpinned by rising capital expenditures in semiconductor manufacturing and accelerating deployment of energy storage systems globally.
Segmentation Analysis of the Semiconductor Graphite Market
The market segments by type into Naturally Occurring Graphite (including flake, lump, and amorphous), Artificial Graphite (spanning synthetic electrodes, powder, and blocks), and Graphite Nanofibers. End-uses encompass Consumer Electronics, Automotive, Aerospace And Defense, Energy Storage, and Semiconductor Manufacturing, with applications ranging from thermal management to semiconductor devices and conductive coatings.
Geographic Distribution and Regional Market Performance
Asia-Pacific dominates the geographic distribution, acting as the epicenter for semiconductor fabrication and battery manufacturing, closely followed by North America and Europe. Regional performance correlates directly with local fab buildouts and government subsidies, with Chinese players like Jiangxi Ningxin New Materials scaling output alongside established Japanese and Western conglomerates.
In-Depth Regional Review of Key Geographies
East Asia leads consumption due to heavy concentration of semiconductor foundries in Taiwan, South Korea, and mainland China. Meanwhile, North American demand surges from domestic fab reshoring initiatives under the CHIPS Act. European markets emphasize sustainable, low-carbon synthetic graphite production, balancing strict REACH compliance with high-end aerospace and automotive demands.
Strategic Positioning of Leading Companies
Firms like Schunk Group, HEG Limited, and Nippon Carbon Co. Ltd. leverage specialized vertical integration to maintain pricing power. Companies such as Superior Graphite and Asbury Carbons Inc. differentiate through advanced particle size engineering, tailoring their naturally occurring and synthetic offerings to exact foundry specifications.
Porter's Five Forces Analysis of Competitive Dynamics
Bargaining power of raw material suppliers is moderate to high due to concentrated needle coke sources, while buyer power remains constrained by the stringent qualification processes required for semiconductor-grade graphite. Threat of substitutes is remarkably low given graphite's unmatched thermal and electrical conductivity at extreme temperatures in cleanroom environments.
SWOT Analysis of the Semiconductor Graphite Sector
Strengths include exceptional thermal shock resistance and high chemical purity. Weaknesses involve energy-intensive graphitization processes. Opportunities lie in graphite nanofibers for next-gen thermal interfaces, while threats include geopolitical trade restrictions on critical raw materials impacting cross-border logistics through major shipping hubs.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with petroleum coke and natural flake extraction, moves through high-temperature graphitization and purification, and culminates in precision machining by specialists like Poco Graphite Inc. and Sinosteel Corporation. End-users receive mission-critical components that dictate yield rates in advanced semiconductor lithography equipment.
Investment Insights and Strategic Recommendations
Our analysis advises investors to focus on greenfield purification technologies and high-purity synthetic graphite block manufacturers equipped to handle sub-micron machining tolerances. Strategic partnerships with regional foundries will be vital for mitigating geopolitical risks and capturing market share in fast-growing artificial intelligence hardware supply chains.
Conclusion and Key Industry Takeaways
The Semiconductor Graphite Market represents a high-barrier, high-growth sector set to reach 3.80 Billion by 2033. Success hinges on technological mastery of ultra-high purification, strategic alignment with semiconductor foundry expansions, and proactive navigation of evolving environmental regulations governing raw material processing.
Research Methodology and Baseline Estimation
Our baseline estimates are triangulated by combining proprietary primary stakeholder interviews with C-level executives at firms like SEC Carbon Ltd. and Fangda Carbon New Material Co. Ltd., cross-referenced against customs trade registries, secondary macroeconomic indicators, and empirical capacity assessments of major global manufacturing plants.
Scope of the Report and Coverage Parameters
This report covers global revenue projections from 2027 to 2033, breaking down market size, growth rates, and competitive positioning across multiple segmentation matrices. Limitations include potential volatility in precursor raw material costs and shifting geopolitical tariffs affecting international trade routes.
Recent Developments and Strategic Industry Moves
Recent market activities feature capacity expansions by Westwater Resources and strategic joint ventures by Pingdingshan Oriental Carbon and Pingdingshan Boxiang Carbon to secure domestic needle coke supplies. These moves reflect an industry-wide push to localize supply chains and accelerate product development for next-generation semiconductor manufacturing nodes.